Get Started!

When a senior needs help with everyday things, like bathing, dressing, meal preparation, and a steady hand around the house, those needs are non-medical. And when the needs are non-medical, options like health insurance, Medicare, or Medicaid often won’t pay for those expenses.
That’s where long-term care insurance comes in. It’s a smart way to prepare for the demands of long-term care, and it can offer real peace of mind as your loved one grows older. These policies reimburse policyholders for services that assist with activities of daily living, so families aren’t carrying the full weight alone when a parent faces a chronic illness or needs extra help with age.
Long-term care benefits in Salem, OR, aren’t limited to in-home care, either. A policy may also help pay for assisted living facilities, nursing home care, and memory care communities. If your loved one already holds a policy, you may be sitting on benefits they’ve paid for and never used.
Filing an LTC insurance claim can be complicated and overwhelming. Most families are reading a policy for the first time during a stressful moment, after a fall, after a hospital stay, after Mom quietly stopped cooking for herself.
ComForCare Home Care has 20 years of experience working with long-term care insurance carriers. We’ve seen how different companies word their requirements, what documentation they ask for, and where claims tend to stall. In most instances, we have relationships with LTCI carriers and can help guide you through the process.
You don’t have to figure out the paperwork on your own. Let us help you navigate your policy.
As an experienced home care agency, we’re a valuable resource for policyholders and their families. Here’s exactly what that support looks like:
Every long-term care insurance policy is different, so we work closely with the policyholder and their insurance provider to understand the specific requirements and coverage. A few things hold across nearly every policy:
Don’t have a policy yet? You’re not behind; you’re early, and that’s an advantage. Genworth produces an annual cost-of-care survey to help families understand and plan for their long-term care needs, and its results have become the foundation for long-term care planning.
Policies are typically purchased through an employer, a long-term care insurance agent, or an insurance agent or broker. When shopping, it helps to think through a few key factors: the benefit amount, how long benefits last, and the elimination period before coverage begins. The policy purchased determines how much care is covered at the time of a claim, usually as a daily or monthly benefit amount, with a maximum payout that accumulates over time.
Buying coverage before a senior’s health changes or an emergency arises gives your family more options when quality care is needed most.
Many long-term care insurance policies reimburse for services that assist with activities of daily living, such as bathing, dressing, or meal preparation. Because every policy is different, we work directly with the policyholder and their insurance provider to confirm what’s covered.
A benefit trigger is typically the inability to perform a certain number of Activities of Daily Living, or cognitive impairment. We have experience with various long-term care insurance policies and can help you explore whether the policyholder meets those requirements.
Some policies allow direct billing from the care provider, while others reimburse the policyholder. We can facilitate either process: submitting invoices directly to the insurer or providing you with the documentation needed to seek reimbursement.
By partnering with a knowledgeable home care agency, policyholders can significantly ease the stress of filing a long-term care insurance claim and make sure they receive the benefits they’re entitled to for their care. We’ll help you understand the policy, assist with the paperwork, and handle billing directly with the insurance company.
Whether you need help understanding the terms of a policy or you’re ready to file a claim, ComForCare is here to support your family every step of the way. If you’re ready to learn more or start a claim, reach out to ComForCare Home Care today.
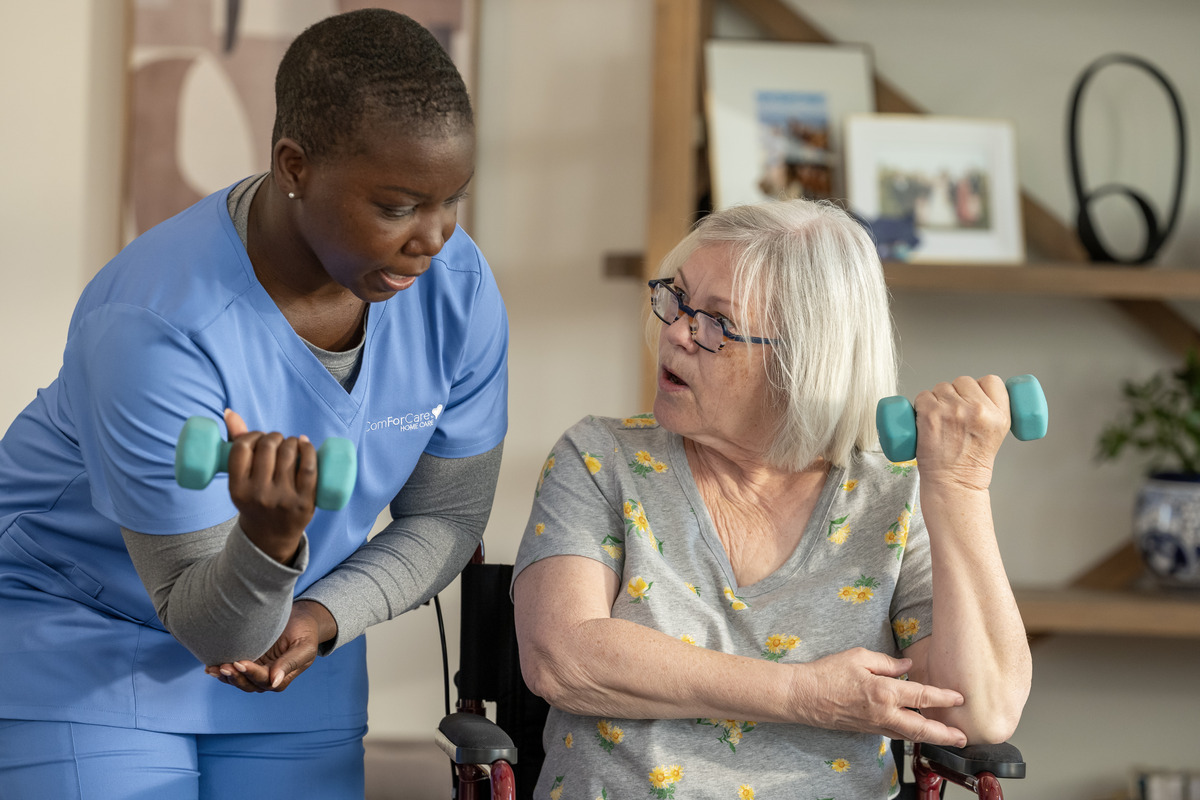
Filing an LTC insurance claim can be complicated and overwhelming. That’s why working with professionals like those at ComForCare can make all the difference. We’ll help you understand your policy, including terms like “elimination period,” “maximum daily benefit,” and more. Plus, we’ll assist with the paperwork and can handle billing directly with the insurance company eliminating this added burden.
Whether you need help understanding the terms of your policy or filing a claim, ComForCare is here to support you every step of the way. And since navigating LTC insurance can be tricky, it’s always a good idea to seek professional help to ensure you’re maximizing your benefits.
If you’re ready to learn more or file a claim, reach out to ComForCare today!
Genworth produces the cost of care survey annually with the intent to help families understand and plan for their long-term care needs. The survey results have become the foundation for long-term care planning.
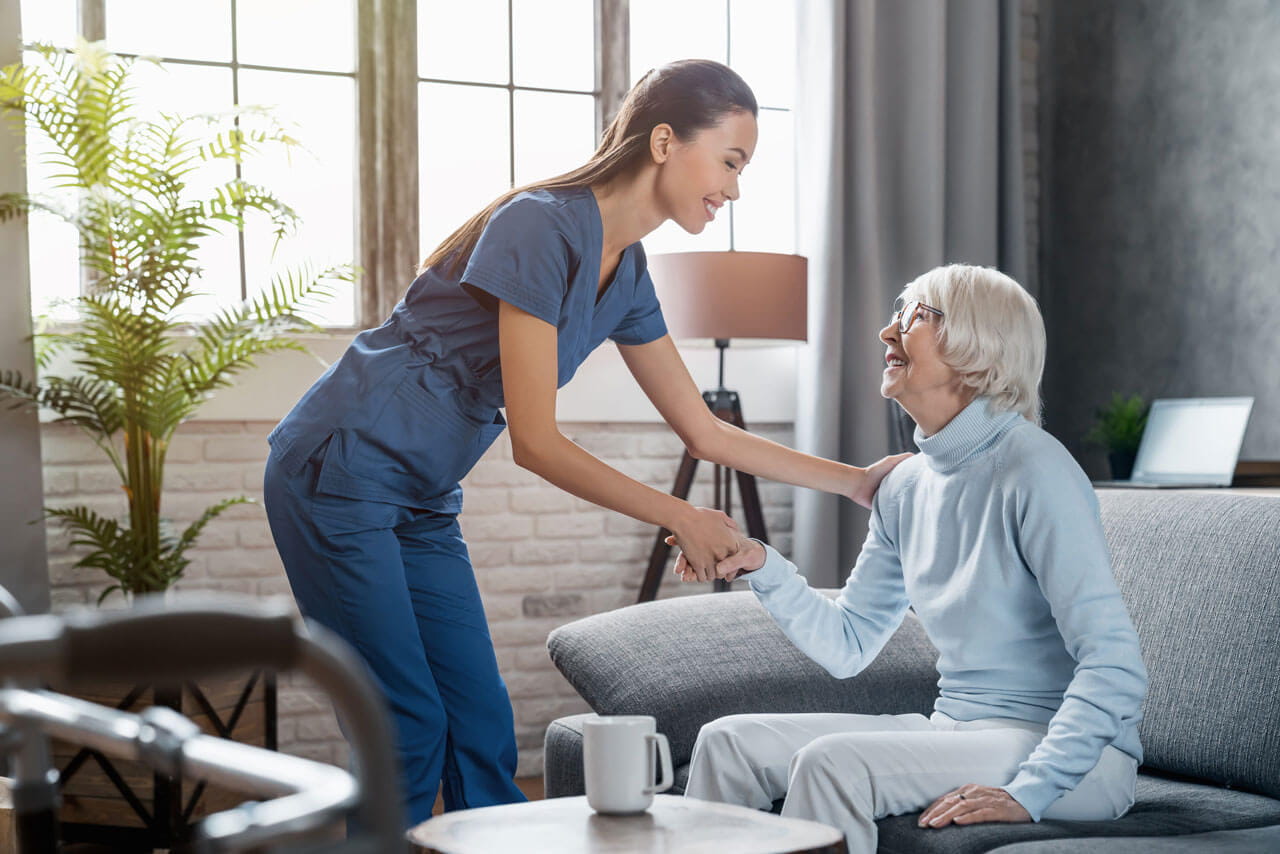
If a senior’s needs are non-medical, in-home care supportive care needs, options like health insurance, Medicare, or Medicaid often won’t pay for those expenses. That’s where long-term care insurance comes in. It’s a smart way to prepare for the financial demands of long-term care and can offer peace of mind as your loved ones grow older.
Long-term care insurance (LTC) policies help by reimbursing policyholders for services that assist with daily living activities, like bathing, dressing, or meal preparation. These benefits can relieve families of the financial burden when a loved one faces chronic illness or simply needs extra help as they age, even if they’re in good health.
LTC insurance covers more than just in-home care. It can also help pay for assisted living facilities, nursing home care, and memory care communities. When shopping for a policy, it’s important to think about a few key factors: the benefit amount (or coverage level), how long benefits last, and the elimination period before coverage kicks in.
The cost of long-term care insurance varies, just like the costs of care itself. Buying coverage before a senior’s health changes or before an emergency arises gives families more options when they need quality care. Since LTC policies can be complicated, it’s helpful to work with a professional—like a ComForCare Home Care expert—to ensure you’re getting the most out of your benefits.
Depending on the policy purchased, it will determine how much care is covered at the time of a claim. This will be covered in the form of a daily or monthly benefit amount and often include a maximum payout in which the policy will pay out in total which is accumulated overtime.
Long-term care insurance policies are typically purchased through an employer, long-term insurance agent or insurance agent or broker.
This is where companies like ComForCare can step in and help. If you’re a senior or someone helping an older adult considering a policy, please give us a call today.
By partnering with a knowledgeable home care agency, policyholders can significantly ease the burden of filing a long-term care insurance claim and ensure they receive the benefits they are entitled to for their car
Each office is independently owned and operated and is an equal opportunity employer.
© 2026 ComForCare Franchise Systems, LLC.