Get Started!

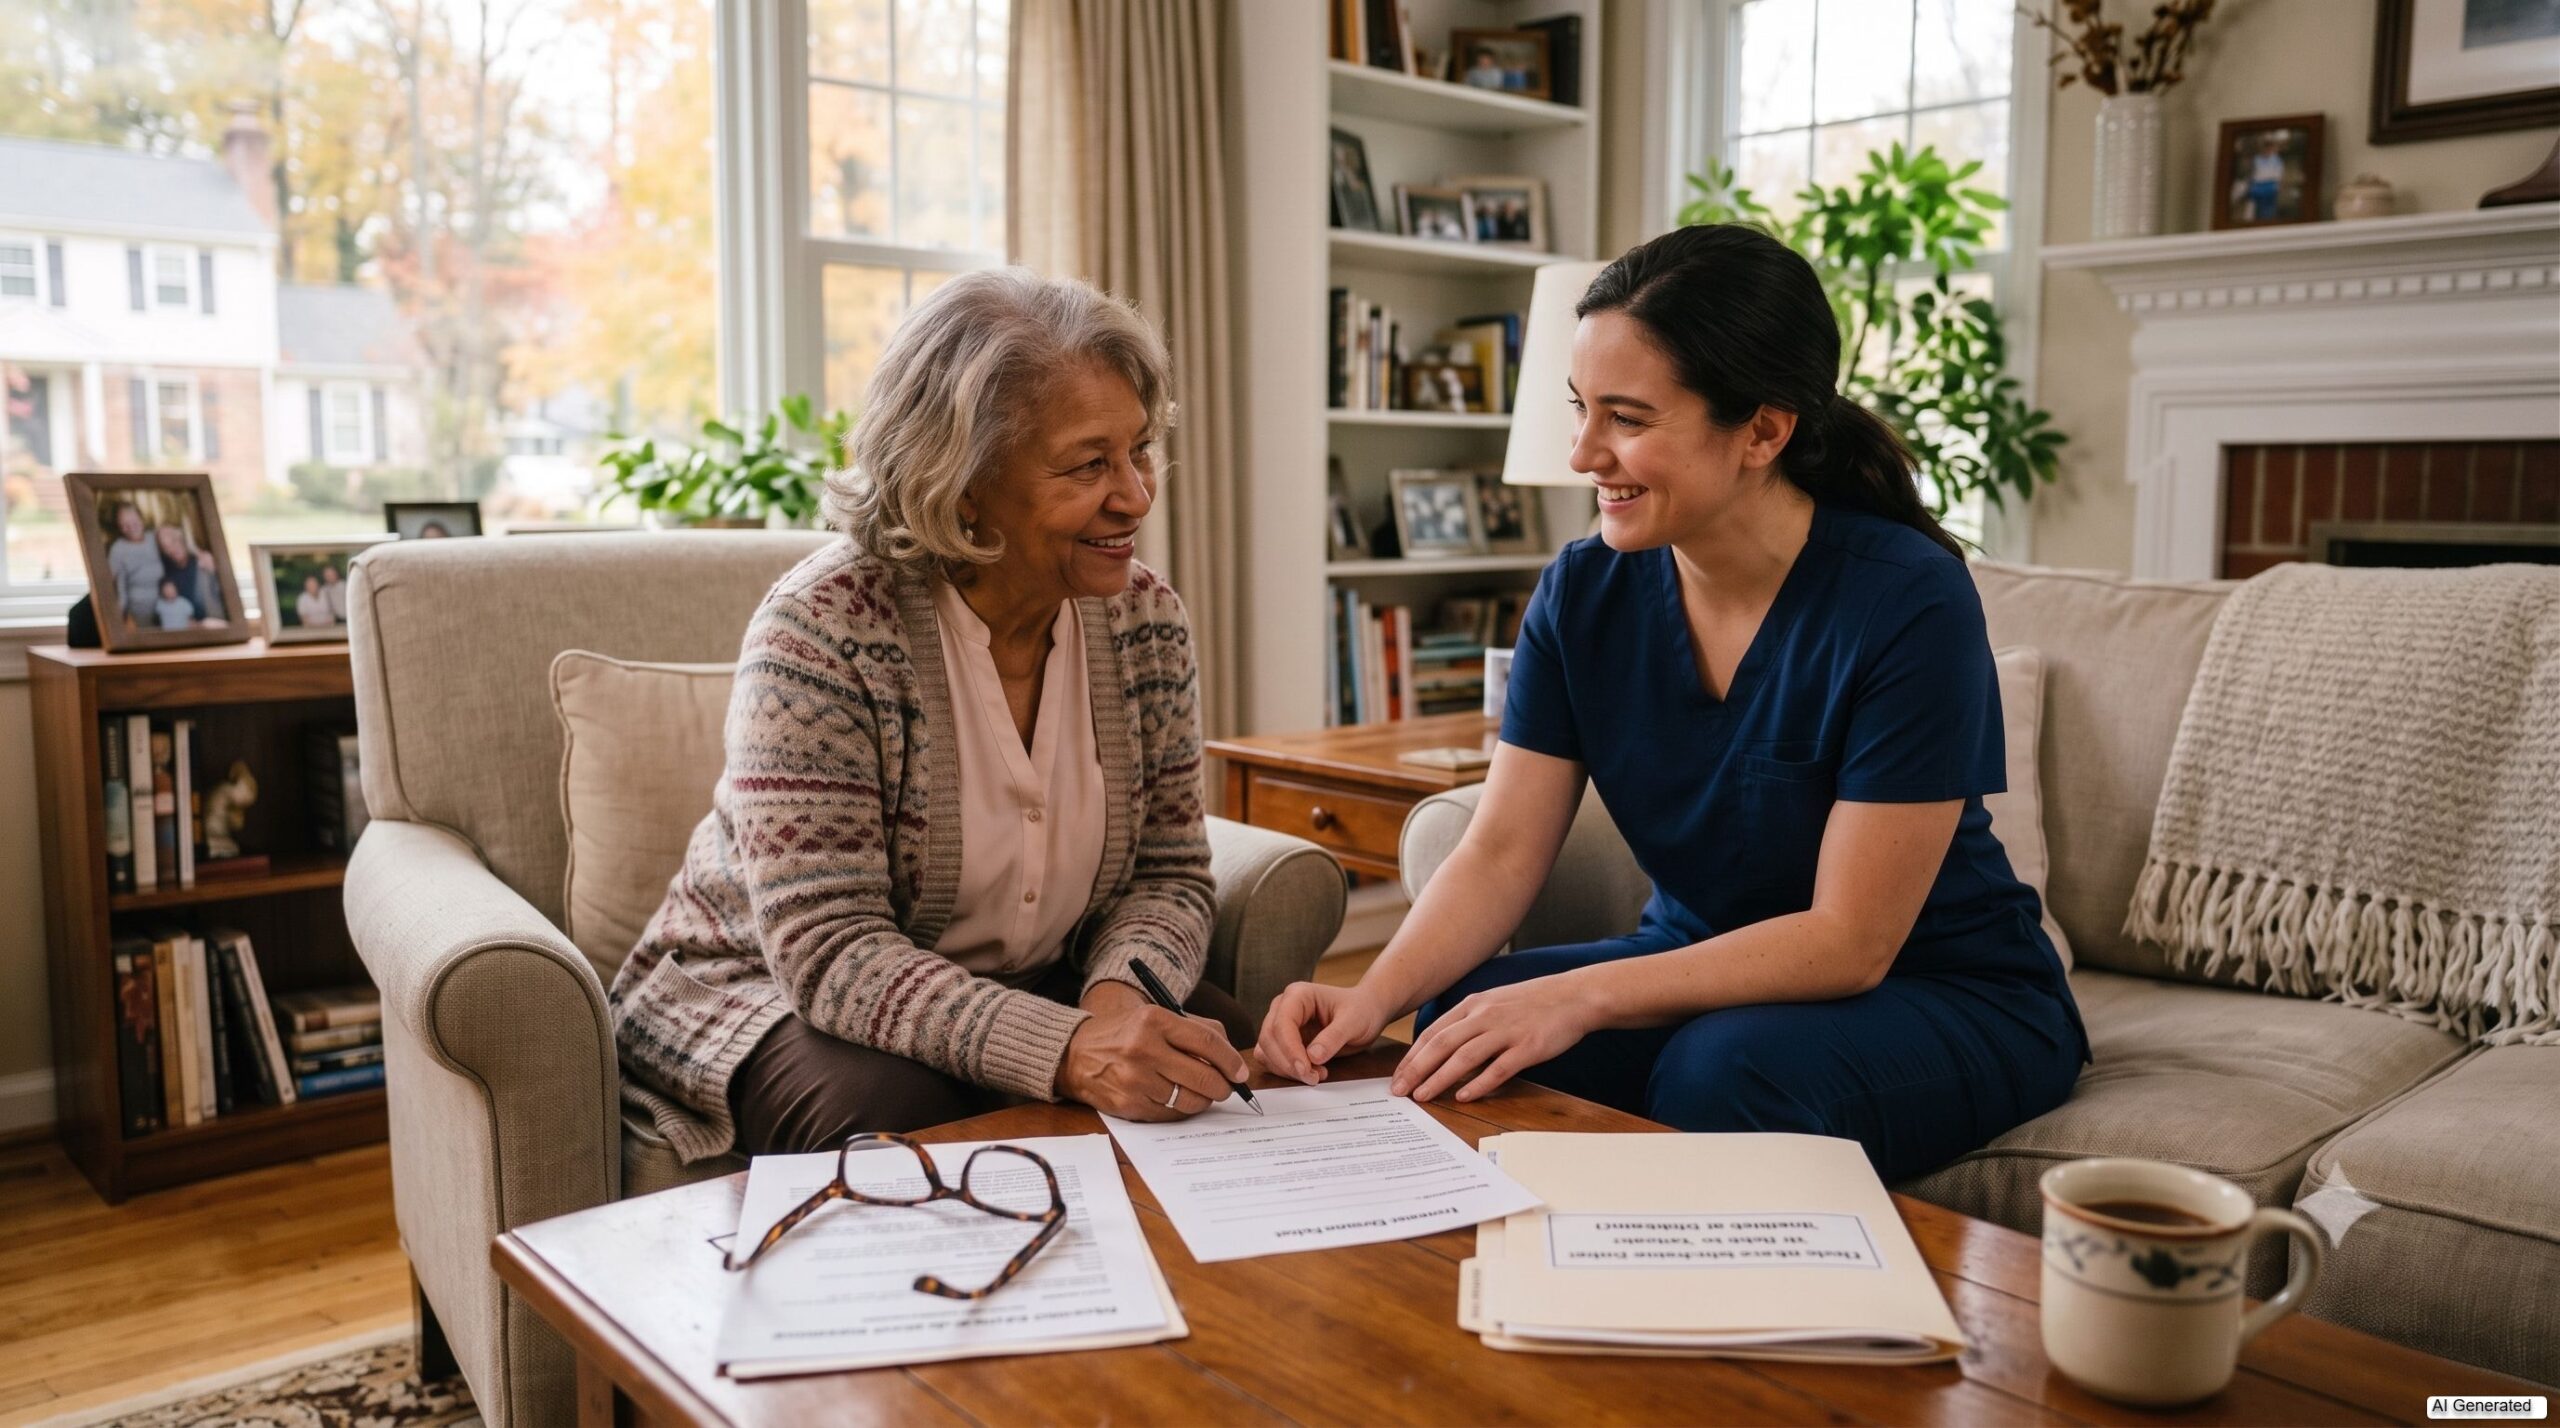
| Quick summary: Many long-term care policies cover in-home care, including personal care, companionship, respite, and dementia support. Benefits may be approved once someone needs help with two or more daily activities or has a documented cognitive impairment, followed by an elimination period that can be roughly 30 to 90 days. Filing a claim typically involves reviewing your policy’s four key numbers, getting a medical assessment, choosing a qualified agency, and submitting documentation. |
Many families assume home care has to come out of pocket, then learn later that a long-term care policy would have covered part of it. Others know a policy exists but have no idea what it pays, when it starts, or who to call first.
This guide covers what long-term care insurance typically pays for at home, what triggers benefits, and how to file a claim.
Many long-term care policies provide benefits for care received at home, though coverage varies by policy. Plans commonly pay for:
Some policies reimburse the policyholder after claims are submitted. Others pay an approved agency directly. Your policy documents will say which, and it changes how you plan.
Most policies don’t begin paying immediately. Two things usually have to be true.
A qualifying need. Most policies require help with two or more Activities of Daily Living – bathing, dressing, eating, transferring, toileting, or continence — or a documented cognitive impairment such as dementia. The cognitive trigger matters: someone with early Alzheimer’s may still manage ADLs independently and still qualify.
The elimination period, typically between 30 to 90 days, requires families to pay for care out-of-pocket before insurance reimbursements begin.
Few policies cover the full cost. Families often combine benefits with veterans’ benefits for eligible veterans and surviving spouses, personal savings, or contributions from family members. Knowing the gap early makes it far easier to plan around.
Insurance is one part of the decision. The other is who walks through the door.
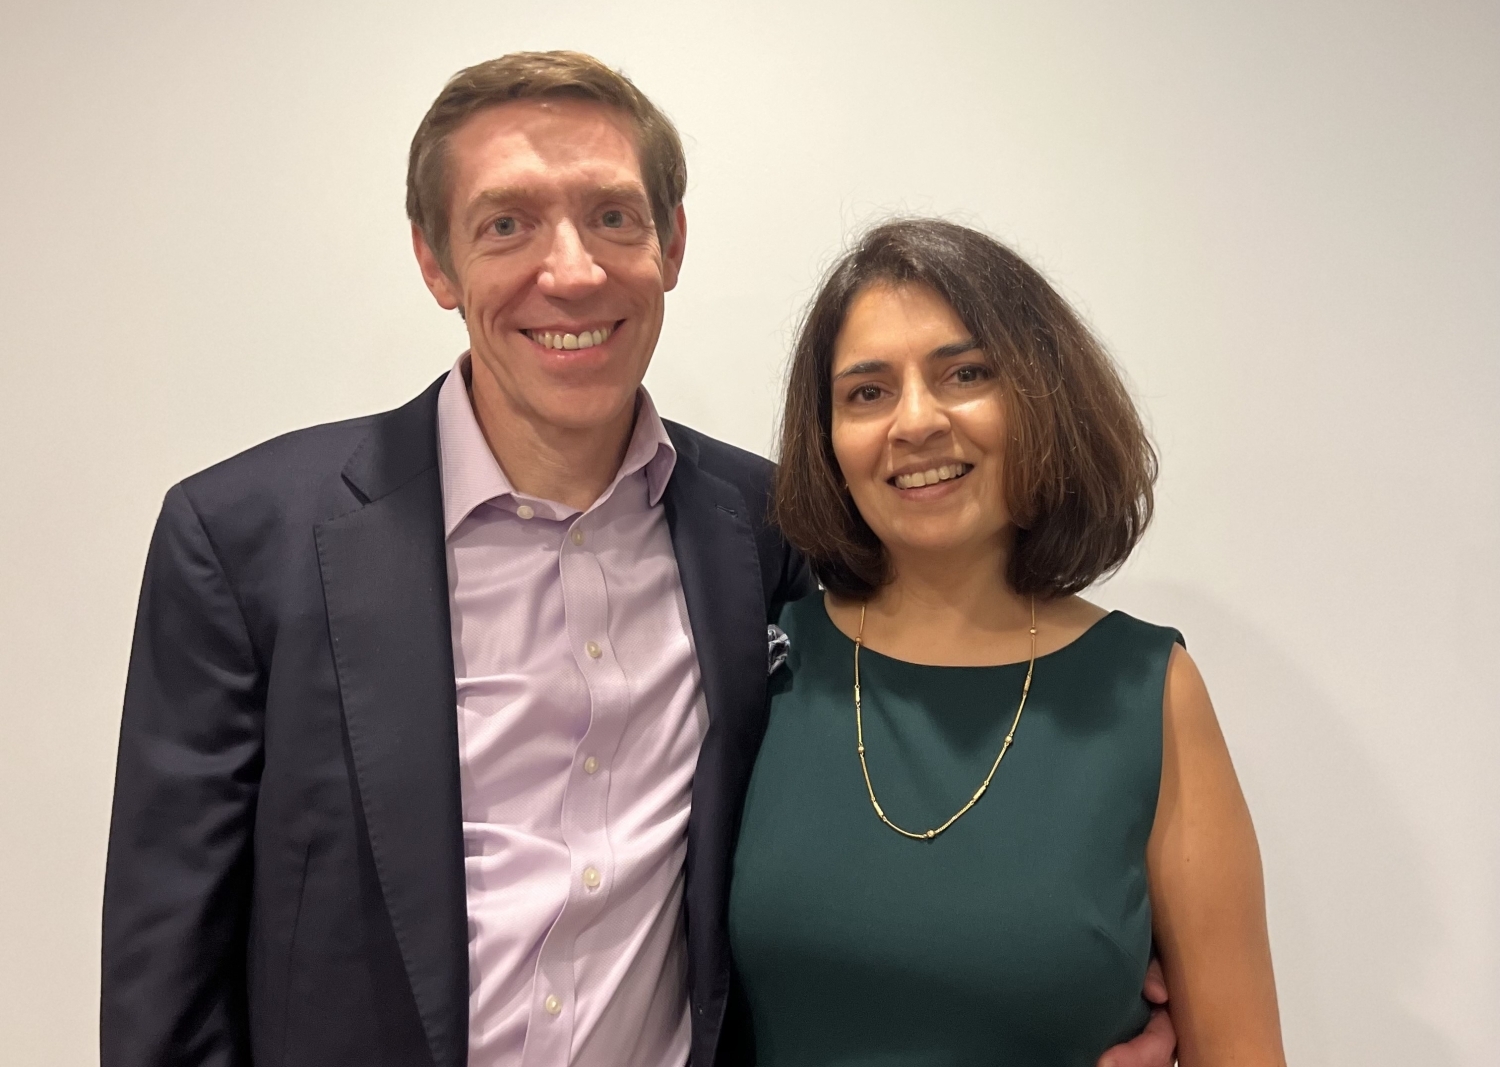
ComForCare South Fairfax is locally owned and led by Tazim Mawji. Our caregivers are carefully screened, professionally trained, and matched with intention to each family, and they train through the DementiaWise® Certified Care Program for families managing memory loss. We help families understand their long-term care benefits and what documentation their insurer will need, and we proudly support veterans in understanding the benefits available to them.
Care begins with a free in-home assessment, where we build the plan around what your loved one actually needs. See our full range of in-home care services or the areas we serve across Fairfax County.
Call (703) 720-9299 to talk through your family’s situation.
“Tazim and her team are really great and I send them special thanks for providing truly excellent home care when I really needed it. I was at first reluctant to have someone in my home since I’m used to living independently. The home health aide they provided, Perpetual (Peppy), was exemplary in all ways: her skills, empathy, communication, attitude, and demeanor. She was simultaneously professional and friendly, and responded to and anticipated both my personal and home care needs with compassion and efficiency. Bravo and thanks again!”
— Susana G., via Google Reviews
1. My parents have dementia but still manage bathing and dressing. Do they qualify?
Eligibility depends on your specific policy terms. Generally, policyholders qualify when a licensed healthcare professional certifies that they require assistance with at least two Activities of Daily Living (ADLs) or need supervision due to cognitive impairment.
2. Does the insurer pay us or the agency?
It depends on the policy. Some reimburse the policyholder after you submit claims, meaning you pay first. Others pay an approved agency directly. Confirm this before care starts.
3. What happens when the lifetime benefit runs out?
This is a very unlikely scenario if anything, owners of Long Term Care policies activate their policies too late and benefits are not utilized. If these benefits run out then can continue, but funding shifts to private pay or other sources. Tracking the remaining balance regularly gives your family time to plan. In our experience and the experience of all ComForCare owners we work with, a policy has never run out of funds while we have provided care.
4. Can we use the policy for respite care only?
Some policies cover respite care so a family caregiver can take a break. Coverage and limits vary, so check the specific language in your plan.
Each office is independently owned and operated and is an equal opportunity employer.
© 2026 ComForCare Franchise Systems, LLC.