Get Started!

ComForCare Home Care has 20 years of experience working with long-term care insurance carriers.
If you are a long-term care insurance policy holder or know someone who is, you may be wondering how it works and how it’ll cover the cost of in-home care. As an experienced home care agency in long-term care insurance, ComForCare is a valuable resource for policyholders and their families who need assistance with navigating the long-term care insurance claim process and understanding how it covers the cost of in-home care. ComForCare Home Care in Marlborough, MA supports policyholders and their families as they put a policy to work for in-home care.
We can help you with:
ComForCare Home Care helps policyholders in Marlborough and surrounding communities, including Berlin, Bolton, Fayville, Framingham, Harvard, Hudson, Maynard, Northborough, Southborough, Stow, Sudbury, and Westborough. Explore more served areas.
Many long-term care insurance policies reimburse services that help with daily living, such as bathing, dressing and meal preparation, and some also help pay for assisted living, nursing home or memory care. What is covered depends on your policy, so review it with your insurer.
2. Does Medicare or health insurance pay for non-medical in-home care?
If a senior’s needs are non-medical, options like health insurance, Medicare or Medicaid often will not pay for those expenses. That is where long-term care insurance can help.
3. What is an elimination period?
It is the initial time after a benefit trigger during which the policyholder pays for care out-of-pocket before insurance benefits begin. It works like a deductible measured in days rather than dollars.
4. How can ComForCare help with a long-term care insurance claim?
We can help you understand the policy’s requirements, gather documentation, work through the elimination period, complete the agency’s sections of claim forms and, with your authorization, communicate with the insurance company.
5. What records does ComForCare provide for a claim?
We keep records of dates of service, tasks performed, clock in/out times and the policyholder’s progress, and we can provide regular service notes and invoices for reimbursement or direct billing.
6. Will the insurance company be able to speak with ComForCare?
With proper authorization, yes. The policyholder will likely need to sign an authorization form that lets the insurance company share information with us. Some insurers also assign a care coordinator, and we can work with that person and provide regular updates.
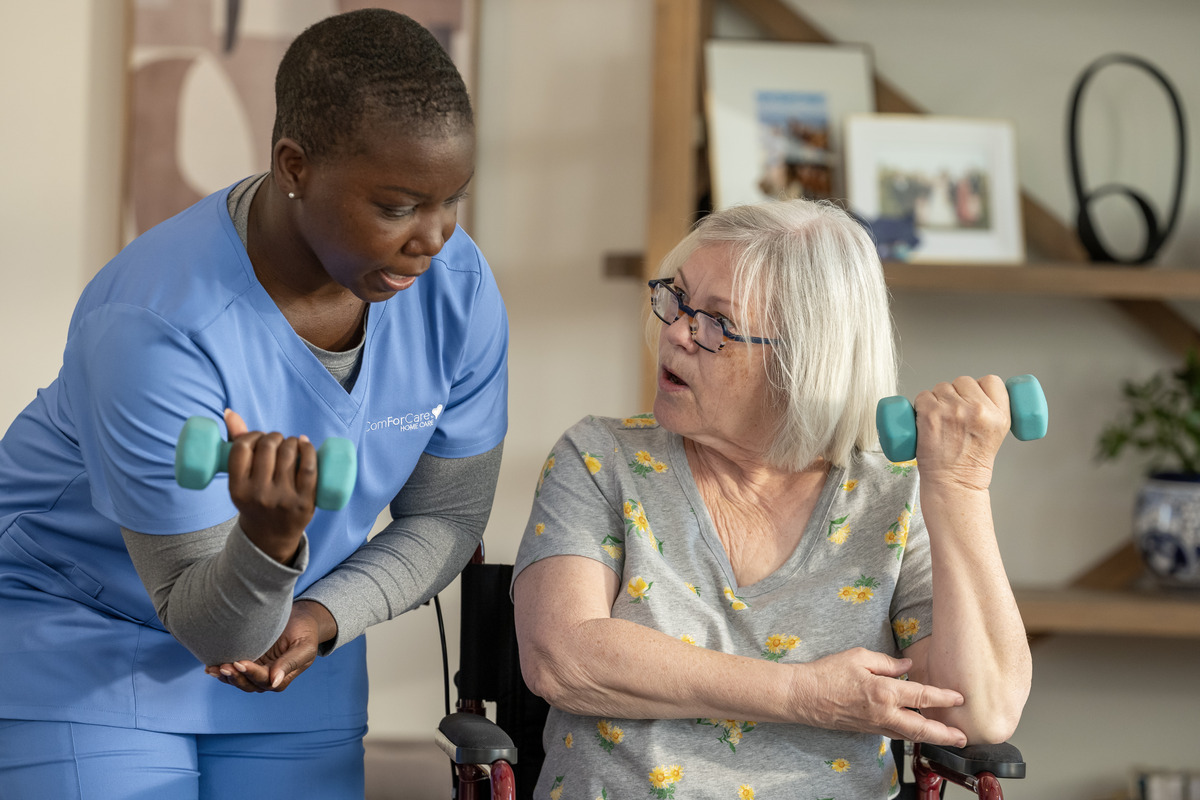
Filing an LTC insurance claim can be complicated and overwhelming. That’s why working with professionals like those at ComForCare can make all the difference. We’ll help you understand your policy, including terms like “elimination period,” “maximum daily benefit,” and more. Plus, we’ll assist with the paperwork and can handle billing directly with the insurance company eliminating this added burden.
Whether you need help understanding the terms of your policy or filing a claim, ComForCare is here to support you every step of the way. And since navigating LTC insurance can be tricky, it’s always a good idea to seek professional help to ensure you’re maximizing your benefits.
If you’re ready to learn more or file a claim, reach out to ComForCare today!
Genworth produces the cost of care survey annually with the intent to help families understand and plan for their long-term care needs. The survey results have become the foundation for long-term care planning.

If a senior’s needs are non-medical, in-home care supportive care needs, options like health insurance, Medicare, or Medicaid often won’t pay for those expenses. That’s where long-term care insurance comes in. It’s a smart way to prepare for the financial demands of long-term care and can offer peace of mind as your loved ones grow older.
Long-term care insurance (LTC) policies help by reimbursing policyholders for services that assist with daily living activities, like bathing, dressing, or meal preparation. These benefits can relieve families of the financial burden when a loved one faces chronic illness or simply needs extra help as they age, even if they’re in good health.
LTC insurance covers more than just in-home care. It can also help pay for assisted living facilities, nursing home care, and memory care communities. When shopping for a policy, it’s important to think about a few key factors: the benefit amount (or coverage level), how long benefits last, and the elimination period before coverage kicks in.
The cost of long-term care insurance varies, just like the costs of care itself. Buying coverage before a senior’s health changes or before an emergency arises gives families more options when they need quality care. Since LTC policies can be complicated, it’s helpful to work with a professional—like a ComForCare Home Care expert—to ensure you’re getting the most out of your benefits.
Depending on the policy purchased, it will determine how much care is covered at the time of a claim. This will be covered in the form of a daily or monthly benefit amount and often include a maximum payout in which the policy will pay out in total which is accumulated overtime.
Long-term care insurance policies are typically purchased through an employer, long-term insurance agent or insurance agent or broker.
This is where companies like ComForCare can step in and help. If you’re a senior or someone helping an older adult considering a policy, please give us a call today.
By partnering with a knowledgeable home care agency, policyholders can significantly ease the burden of filing a long-term care insurance claim and ensure they receive the benefits they are entitled to for their car
Each office is independently owned and operated and is an equal opportunity employer.
© 2026 ComForCare Franchise Systems, LLC.